Gold IRA withdrawals follow standard IRA rules. From a traditional gold IRA, withdrawals are taxed as income, and before 59½ most also face a 10% additional tax. Qualified Roth withdrawals are tax-free.
What's different is how you take the money: you can sell metal and withdraw cash, or take the coins and bars themselves as an in-kind distribution.
Withdrawal Rules at a Glance
| Situation | Traditional Gold IRA | Roth Gold IRA |
|---|---|---|
| Before 59½ | Income tax plus 10% in most cases | Contributions tax-free; earnings may be taxed and penalized |
| 59½ and older | Income tax only | Tax-free if five-year rule is met |
| From 73 (75 if born 1960+) | RMDs required | No RMDs for the original owner |
| In-kind metal | Value taxed as income | Qualified distributions tax-free |
Cash or Metal?
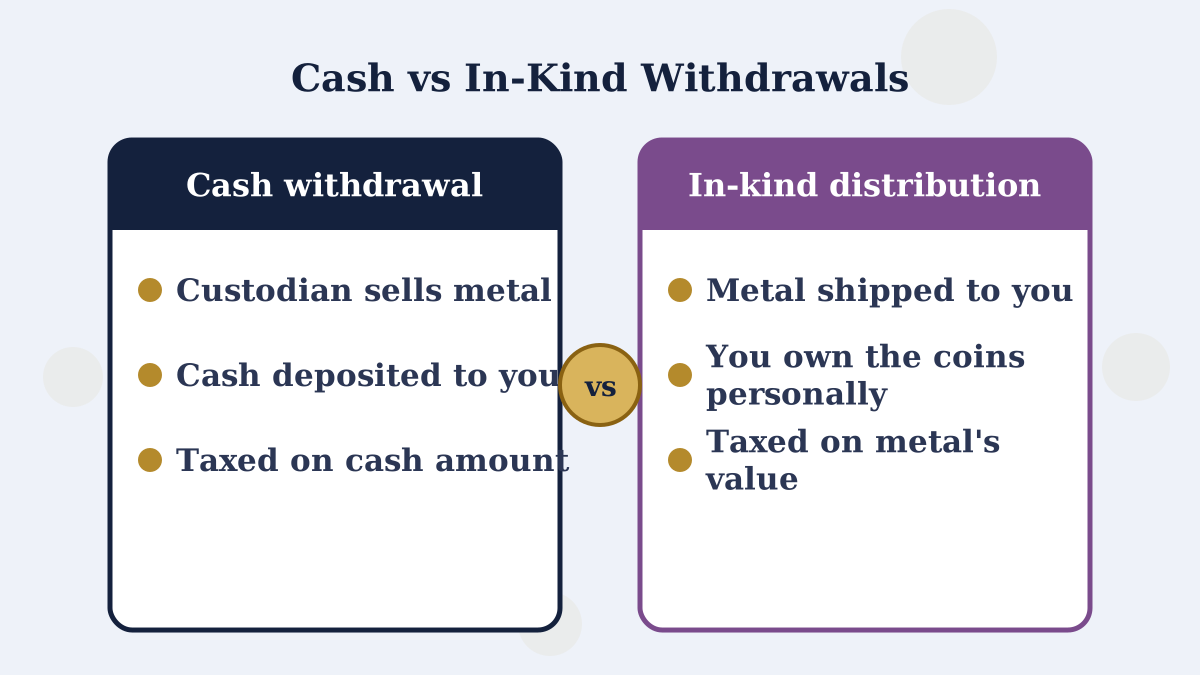
Cash withdrawal: you direct the custodian to sell metal, the proceeds land in the IRA and the custodian sends you cash.
In-kind distribution: the custodian has the depository ship specific coins or bars to you. From a traditional IRA, the metal's value on that date is taxable. See our physical delivery guide.
Early Withdrawal Exceptions
The 10% additional tax doesn't apply in certain situations, including:
- Total and permanent disability.
- Unreimbursed medical expenses above a share of income.
- A first-time home purchase, up to a $10,000 lifetime limit.
- Qualified higher education expenses.
- Substantially equal periodic payments over your life expectancy.
- Certain other situations added in recent law, such as some emergency and disaster withdrawals.
Income tax still applies to traditional IRA withdrawals. Rules are detailed, so check with a tax professional first.
How to Request a Withdrawal
- Decide Cash or Metal
And how much.
- Contact Your Custodian or Gold Company
Complete the distribution form.
- Sell or Ship
The custodian sells metal for cash, or arranges delivery.
- Choose Withholding
For traditional IRAs, you can elect federal withholding.
- Keep Records
You'll receive Form 1099-R in January.
Planning for Flexibility
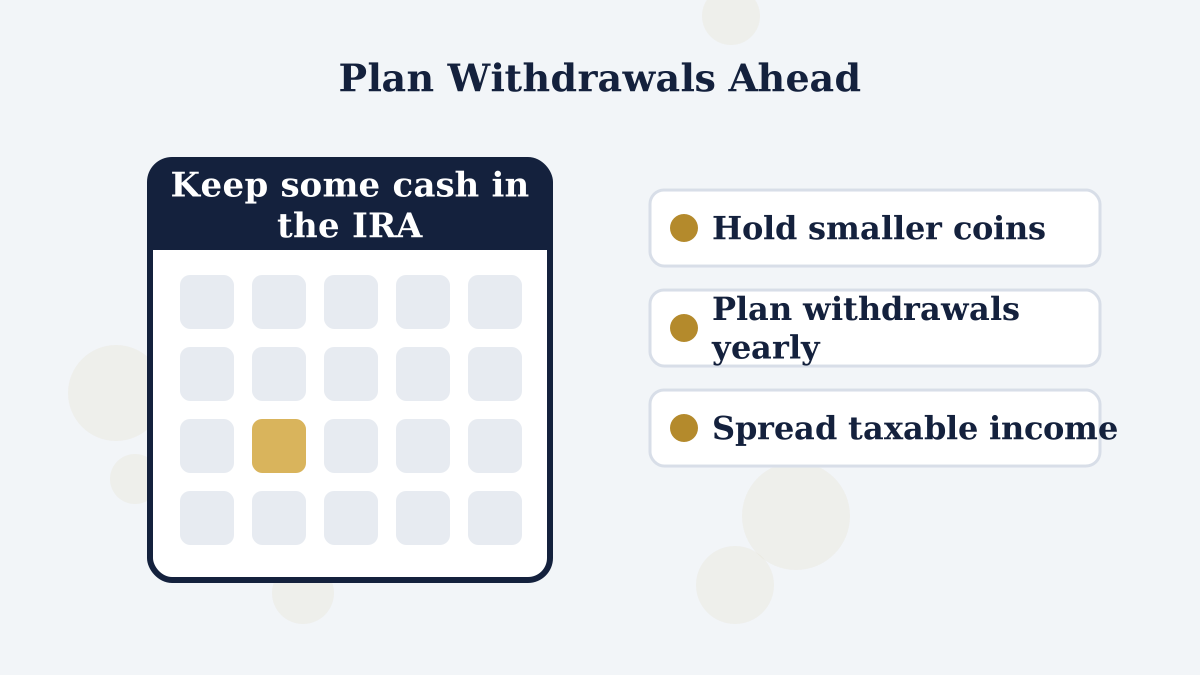
Large bars can't be partly withdrawn, and selling in a hurry may mean a poor price. Many savers keep a cash buffer or some 1 oz coins in the IRA for withdrawals and RMDs. Spreading withdrawals over several years can also keep you in a lower tax bracket.
Costs of Withdrawing
Expect a distribution fee and, for in-kind delivery, shipping and insurance. Noble Gold lists $75 for in-kind distributions and $250 to close an account. When selling, you'll face the dealer's buyback price. See our how to sell a gold IRA guide.
Roth Withdrawal Order
Roth withdrawals come out in a set order: contributions first, then conversions, then earnings. Contributions are always tax-free. Converted amounts withdrawn within five years of conversion may face the 10% penalty if you're under 59½. Earnings are tax-free only for qualified withdrawals.
An Example
Say you're 62 and want $8,000 from your traditional gold IRA. You direct the custodian to sell about $8,000 of metal. The cash lands in the IRA, and the custodian sends it to you, withholding 10% for federal tax if you elect it. The $8,000 is taxable income for the year, but there's no early penalty because you're over 59½.
If you'd rather have the coins, you could instead take about $8,000 worth of Gold Eagles in kind. The tax result is the same: their value on the distribution date is income.
Gold IRA Withdrawal Rules FAQs
When can I withdraw from a gold IRA without penalty?
Generally from age 59½. Before that, most withdrawals face a 10% additional tax unless an exception applies.
Can I take my gold out of the IRA?
Yes. You can take an in-kind distribution, and the custodian has the metal shipped to you. From a traditional IRA, its value is taxable income.
How long does a gold IRA withdrawal take?
Often several business days to a couple of weeks, depending on whether metal must be sold first or shipped to you.
Are Roth gold IRA withdrawals taxed?
Qualified withdrawals, after 59½ and once the five-year rule is met, are tax-free. Contributions can be withdrawn at any time tax-free.
The Bottom Line
Gold IRA withdrawals work like any IRA's, with the added choice of taking cash or metal. Wait until 59½ where possible, plan for RMDs and keep some flexibility in smaller coins or cash.