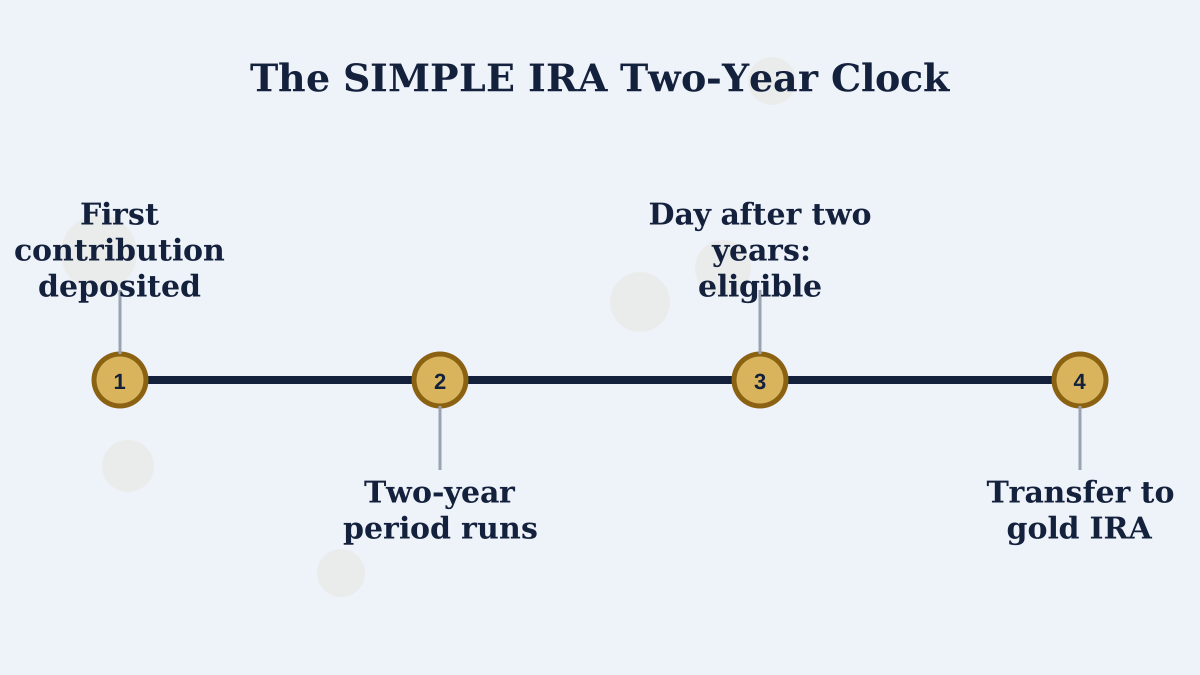
A SIMPLE IRA can move into a gold IRA, but only after two years of participation. The clock starts on the date your first contribution is deposited into a SIMPLE IRA under your employer's plan. After that, a direct transfer into a traditional self-directed gold IRA is tax-free.
Move too early and the IRS treats it as a taxable distribution, with a 25% additional tax if you're under 59½, instead of the usual 10%. That's the one mistake to avoid.
How the Two-Year Rule Works
| Move | During the Two Years | After the Two Years |
|---|---|---|
| To another SIMPLE IRA | Allowed, tax-free | Allowed, tax-free |
| To a traditional gold IRA | Treated as taxable distribution | Allowed, tax-free by direct transfer |
| To a Roth gold IRA | Not allowed as a rollover | Allowed as a taxable Roth conversion |
| Cash withdrawal under 59½ | Taxed plus 25% additional tax | Taxed plus 10% additional tax |
The period is counted from your first deposit, not from the start of a calendar year. If you change employers and join a new SIMPLE IRA plan, that plan's account may run its own clock.
Step-by-Step After Two Years
- Confirm Your First Contribution Date
Check your earliest SIMPLE IRA statement or ask your custodian.
- Open a Traditional Self-Directed Gold IRA
SIMPLE money moves into a traditional IRA, not a SIMPLE gold IRA.
- Sell What You're Moving
Most custodians transfer cash.
- Request a Direct Transfer
Your new custodian sends the request.
- Buy IRA-Eligible Metal
Choose bullion and confirm storage.
What If You're Still Inside the Two Years?
You have three choices: wait, move to another SIMPLE IRA that can hold metals (rare), or use other savings for gold. Most people simply wait. Use the time to research companies and decide how much to move.
If you have other IRAs or an old 401(k), you could fund a gold IRA from those instead and add SIMPLE money later.
Taxes After the Move
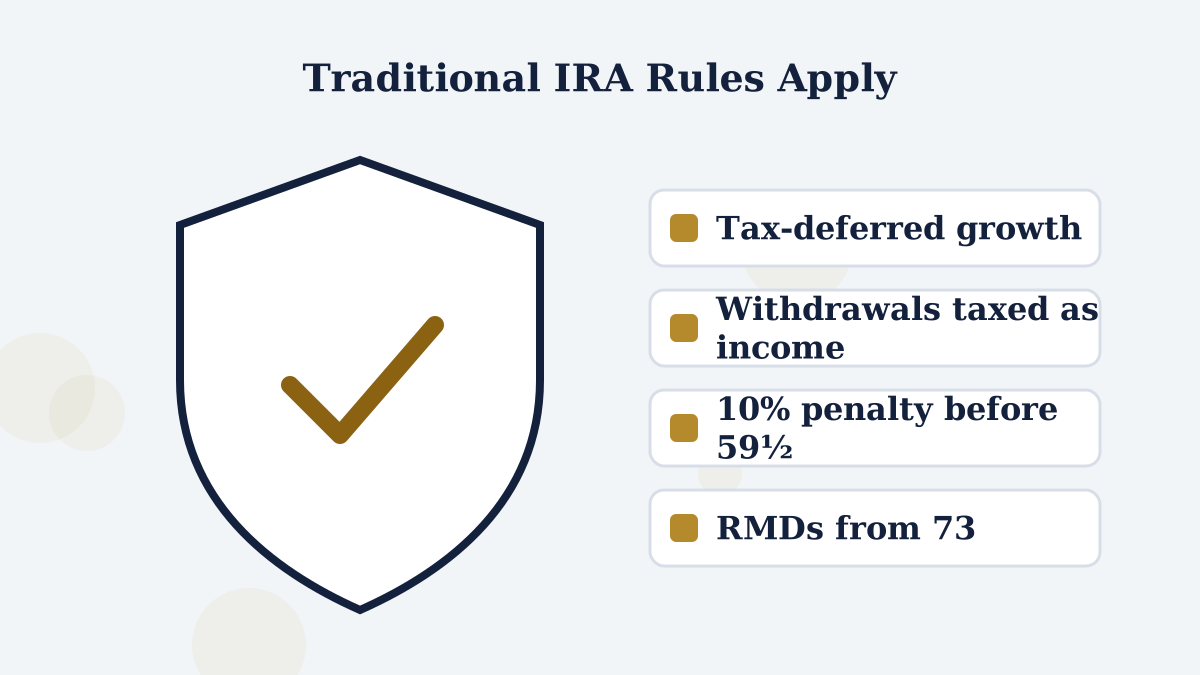
Once in a traditional gold IRA, the money follows traditional IRA rules: tax-deferred growth, withdrawals taxed as income, a 10% penalty before 59½ in most cases, and RMDs from 73. See our withdrawal rules guide.
Keeping Your SIMPLE Plan Going
Moving part of your balance doesn't end your participation. Your employer's contributions and your salary deferrals can keep going into the SIMPLE IRA. You can make another transfer later as your balance grows, since direct transfers aren't limited.
Costs and Minimums
SIMPLE IRA balances are often smaller than 401(k) balances, and gold IRAs carry flat fees. Noble Gold's IRA minimum is $20,000, and its yearly fees total about $285. If your SIMPLE balance is small, you might wait until it grows or combine it with another IRA transfer. Our fee calculator can help.
An Example of the Timing
Say your first SIMPLE IRA contribution was deposited on March 15, 2025. Your two-year period runs through March 14, 2027. A transfer to a traditional gold IRA on or after March 15, 2027 is tax-free.
If you moved the money on, say, January 10, 2027 instead, and you were 50, the IRS would treat it as a taxable distribution with a 25% additional tax. On $25,000, that's $6,250 in additional tax alone, before income tax. A few weeks' patience avoids it.
Employer Considerations
Your employer chooses the financial institution for the SIMPLE IRA plan, but after two years you're free to move your balance. Moving money out doesn't affect your employer's required contributions to your SIMPLE IRA going forward.
SIMPLE IRA to Gold IRA FAQs
Can I roll my SIMPLE IRA into a gold IRA?
Yes, after two years of participation. Once that period ends, a SIMPLE IRA can be transferred into a traditional self-directed gold IRA tax-free.
When does the two-year clock start?
On the date your first contribution is deposited into a SIMPLE IRA under your employer's plan, not the date you were hired.
What happens if I move it too early?
A transfer to a non-SIMPLE IRA within the two years is treated as a taxable distribution, with a 25% additional tax if you're under 59½, instead of the usual 10%.
Can I keep contributing to my SIMPLE IRA after moving some to gold?
Yes. You can move part of your SIMPLE IRA balance after two years and keep participating in your employer's plan.
The Bottom Line
SIMPLE IRAs can fund a gold IRA, but only after the two-year period from your first contribution. Wait it out, then use a direct transfer into a traditional gold IRA, and you'll avoid the 25% penalty trap entirely.