A 403(b) is the workplace retirement plan used by public schools, hospitals, universities and other nonprofits. Like a 401(k), it can roll into a gold IRA once the money is eligible to leave the plan, usually after you leave the employer or, in many plans, once you reach 59½ while still working.
Use a direct rollover to a matching account type and the move is tax-free. The main 403(b)-specific catch is that some plans hold money in annuity contracts that may carry surrender charges.
Eligibility
| Situation | Can You Roll Over? |
|---|---|
| Left your employer | Yes |
| Still working, 59½ or older | Often, if the plan allows in-service distributions |
| Still working, under 59½ | Rarely |
| Retired | Yes |
Your plan document controls what's allowed while you're still employed. Ask your plan administrator or HR office.
Step-by-Step
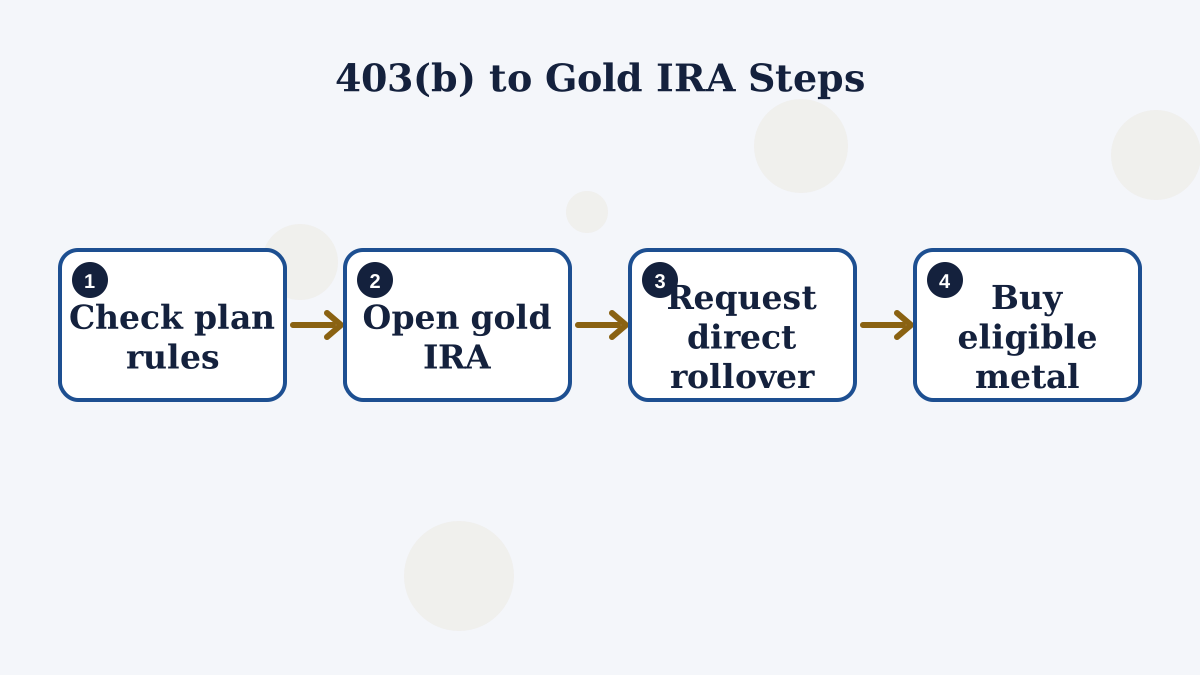
- Check Eligibility and Charges
Confirm you can take a distribution and whether any surrender charges apply.
- Open a Self-Directed Gold IRA
Traditional for pre-tax 403(b) money; Roth for Roth 403(b) money.
- Request a Direct Rollover
Ask the 403(b) provider to pay your new custodian directly.
- Buy IRA-Eligible Metal
Once funds arrive, choose bullion and confirm storage.
Taxes
- Pre-tax 403(b) to traditional gold IRA: no tax by direct rollover.
- Roth 403(b) to Roth gold IRA: no tax.
- Pre-tax 403(b) to Roth gold IRA: taxable Roth conversion.
- Check paid to you: 20% withheld, with 60 days to roll over the full amount.
You'll receive a Form 1099-R from the 403(b) provider showing a direct rollover.
403(b) Annuity Contracts
Many 403(b) plans, especially in schools, hold money in annuity contracts from insurance companies. Some charge surrender fees if you move money in the first several years. Some also carry guaranteed benefits you'd give up.
Ask your provider for the surrender schedule and any benefits tied to the contract. If charges are high, you might wait or move only the part that's free to leave.
457(b) Plans Compared
State and local government workers may have a 457(b) instead of, or as well as, a 403(b). Governmental 457(b) money can be rolled into an IRA after you leave. But 457(b) withdrawals after separation aren't hit by the 10% early penalty, while IRA withdrawals before 59½ usually are.
If you might need the money before 59½, consider leaving part of it in the 457(b).
Costs to Compare
403(b) plan costs vary a lot, from very low-cost fund platforms to higher-cost annuity products. A gold IRA has flat setup, custodian and storage fees plus a dealer spread. Noble Gold publishes $50 setup, $125 a year for maintenance and $160 a year for storage. See our gold IRA fees guide.
How Much to Move
Many educators and public employees also have a pension, which acts like a steady income source. That can make a modest gold allocation fit more easily. Most guidance suggests keeping metals to a small share of total savings. See our how much gold to hold guide.
Common 403(b) Rollover Mistakes
- Requesting a check to yourself, which triggers 20% withholding and a 60-day deadline.
- Ignoring surrender charges on older annuity contracts.
- Rolling a 457(b) too early and losing penalty-free access before 59½.
- Moving Roth and pre-tax money into the same account. They need separate IRAs of matching types.
- Forgetting outstanding loans, which may become taxable if not repaid when you leave.
Timing
Most 403(b) providers process direct rollovers within one to three weeks, though some require paper forms or extra signatures. Our rollover timeline guide walks through each stage.
403(b) to Gold IRA FAQs
Can I roll my 403(b) into a gold IRA?
Yes, once the money is eligible to leave the plan, usually after you leave the employer or reach 59½ if the plan allows in-service distributions.
Is a 403(b) to gold IRA rollover taxable?
Not if you use a direct rollover to a matching account type, such as pre-tax 403(b) to a traditional gold IRA.
Can I roll over a 403(b) annuity contract?
Often yes, but some 403(b) annuity contracts have surrender charges. Ask your provider before requesting a rollover.
What about a 457(b) plan?
Governmental 457(b) plans can also roll into an IRA after you leave. Note that 457(b) withdrawals after separation aren't subject to the 10% early penalty, but money rolled into an IRA generally is before 59½.
The Bottom Line
A 403(b) rolls into a gold IRA much like a 401(k): confirm eligibility, open the gold IRA, request a direct rollover and buy eligible metal. Check for annuity surrender charges and keep the 457(b) penalty difference in mind if it applies.